Glen Oaks Village Coops for Sale
A coop community in Glen Oaks, Queens — tracked building by building: live listings, what units actually sell for, carrying costs, and what its board expects from buyers.
What is Glen Oaks Village?
Glen Oaks Village is a coop development in Glen Oaks, Queens. The community is managed by Self-managed (Glen Oaks Village Owners, Inc.; 9-member volunteer board).
A self-managed garden-style co-op of 2,904 apartments in 134 buildings across 110 acres, built in 1947 as post-WWII housing and converted to a cooperative in 1981.
Amenities per the official Glen Oaks Village site (glenoaksvillage.com).
Financing this building
Stated on 79% of 156 recorded sales.
Set by the co-op board and subject to change at any time. Confirm with the managing agent before making an offer.
About this building
- Built
- 1950
- Style
- Garden
- Typical unit
- 721 sq ft
- Typical maintenance
- $800/mo
- Pets
- Cats OK, Dogs OK
- Laundry
- Common Area
- Subletting
- Allowed
- Stories
- 2
- Basement
- No
- Garage
- Yes
- Flip tax
- No
- Board approval
- Yes
- Income floor
- $75,000
- Heating
- Hot Water, Natural Gas
- Cooling
- Wall Unit(s)
Amenities
Maintenance includes
Compiled from 54 recorded listings in this development. Building details can change — confirm with the managing agent.
Counts and medians cover coops inside Glen Oaks Village specifically, measured from OneKey MLS records as of October 2026. Medians are rounded — individual units vary by line, floor, and condition.
What home styles does Glen Oaks Village offer?
Compiled from OneKey MLS records of coop sales and listings inside Glen Oaks Village over the past 24 months — layouts the building actually trades, not an official floor-plan list. Medians rounded and shown only with 5+ sales.
What is for sale in Glen Oaks Village right now?
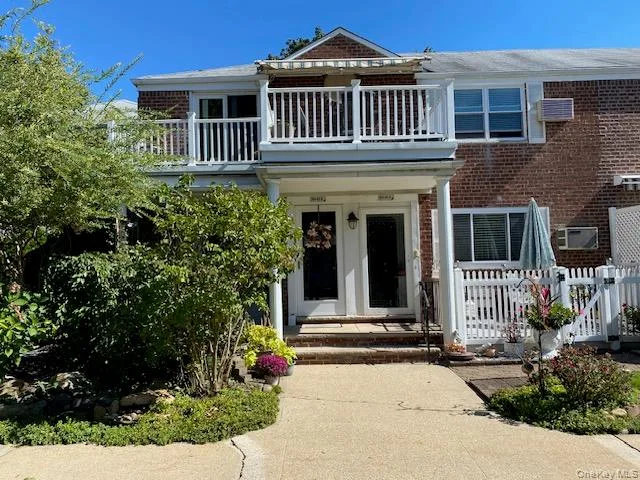 $490K
264-63 Langston Avenue #2nd floor
Listing courtesy of Miller & Miller Real Estate
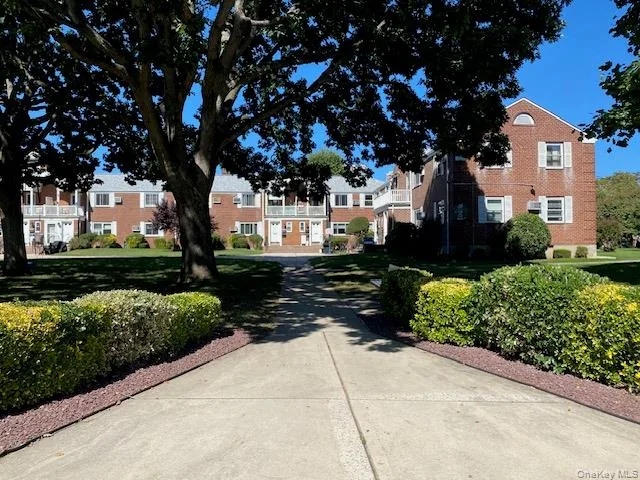 $460K
73-61 260th Street #H-1
Listing courtesy of Miller & Miller Real Estate
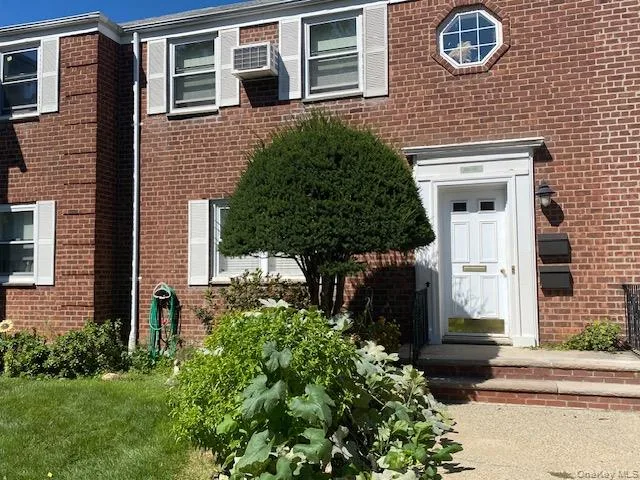 $285K
260-45 73rd Avenue #A-1
Listing courtesy of Miller & Miller Real Estate
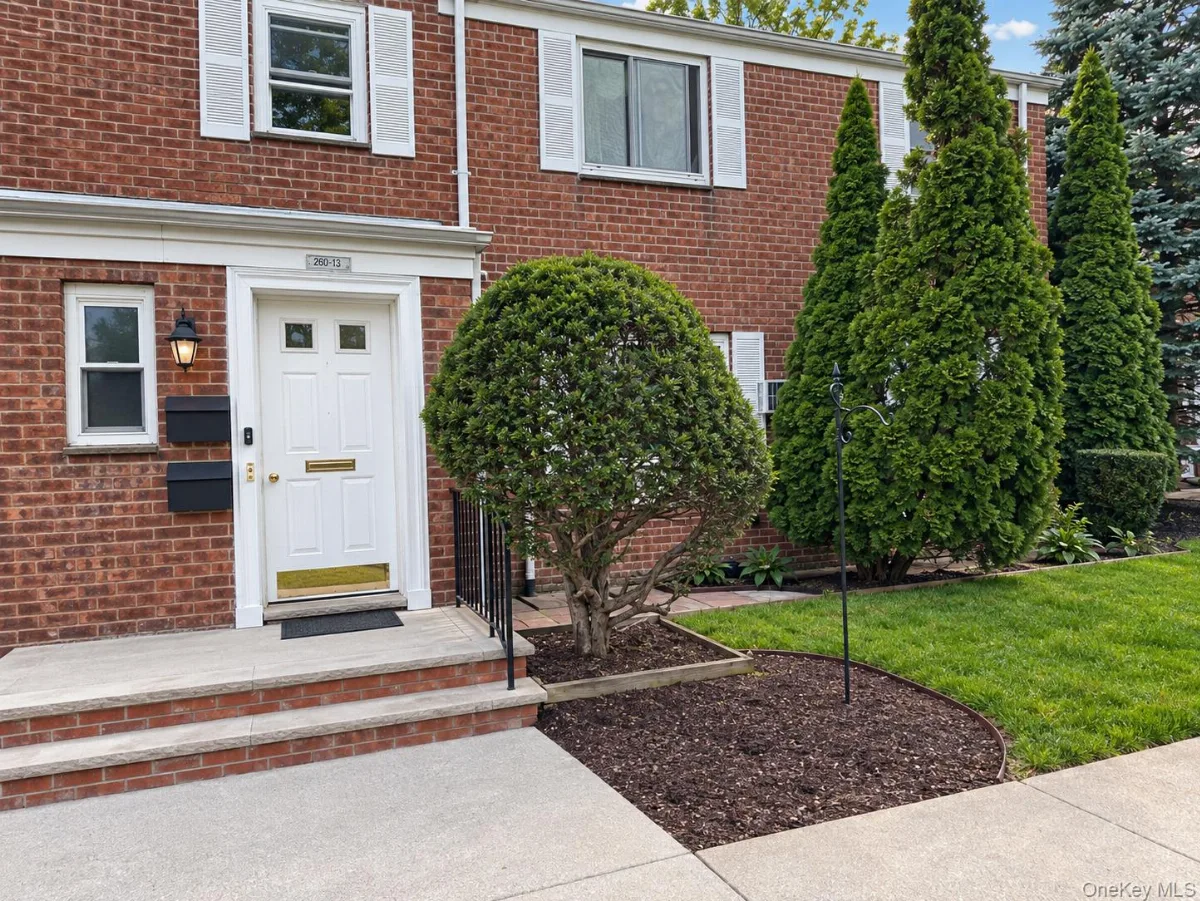 $425K
260-13 74th Avenue #1
Listing courtesy of S H V Real Estate Corp
 $390K
260-55 Langston Avenue #GV120-E
Listing courtesy of Floral Homes Inc
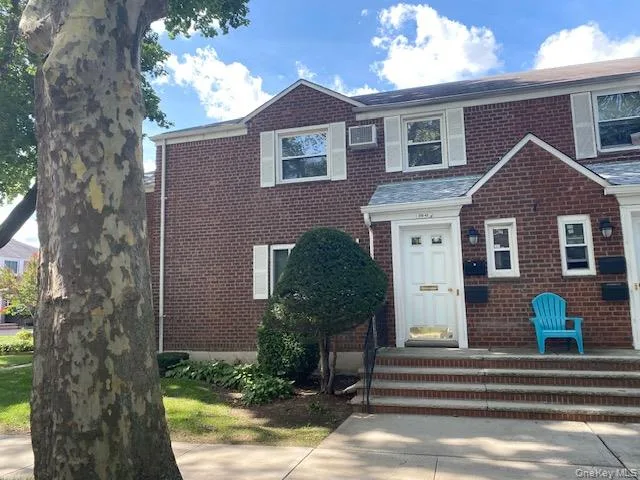 $360K
255-43 73rd. Avenue #B-2
Listing courtesy of Miller & Miller Real Estate
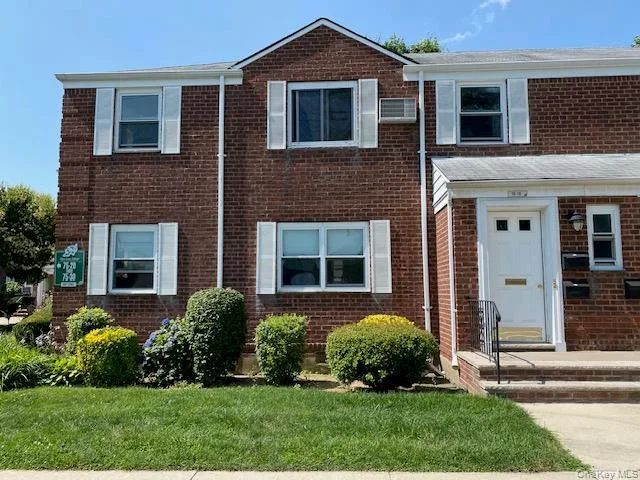 $400K
75-18 263rd #G-1
Listing courtesy of Miller & Miller Real Estate
 $359K
74-43 260 Street #2
Listing courtesy of Voro LLC
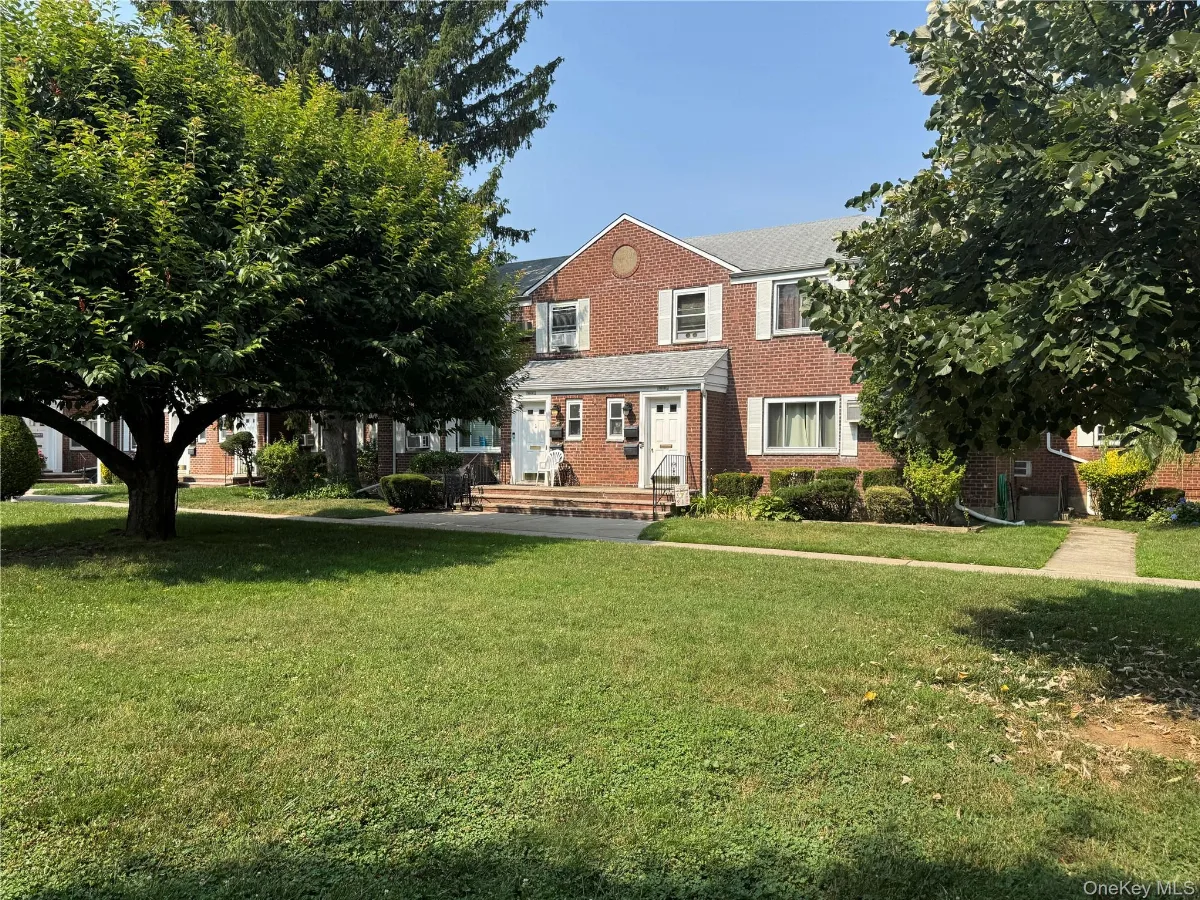 $360K
260-38 73 Avenue #B1
Listing courtesy of Century 21 Milestone Team Rlty
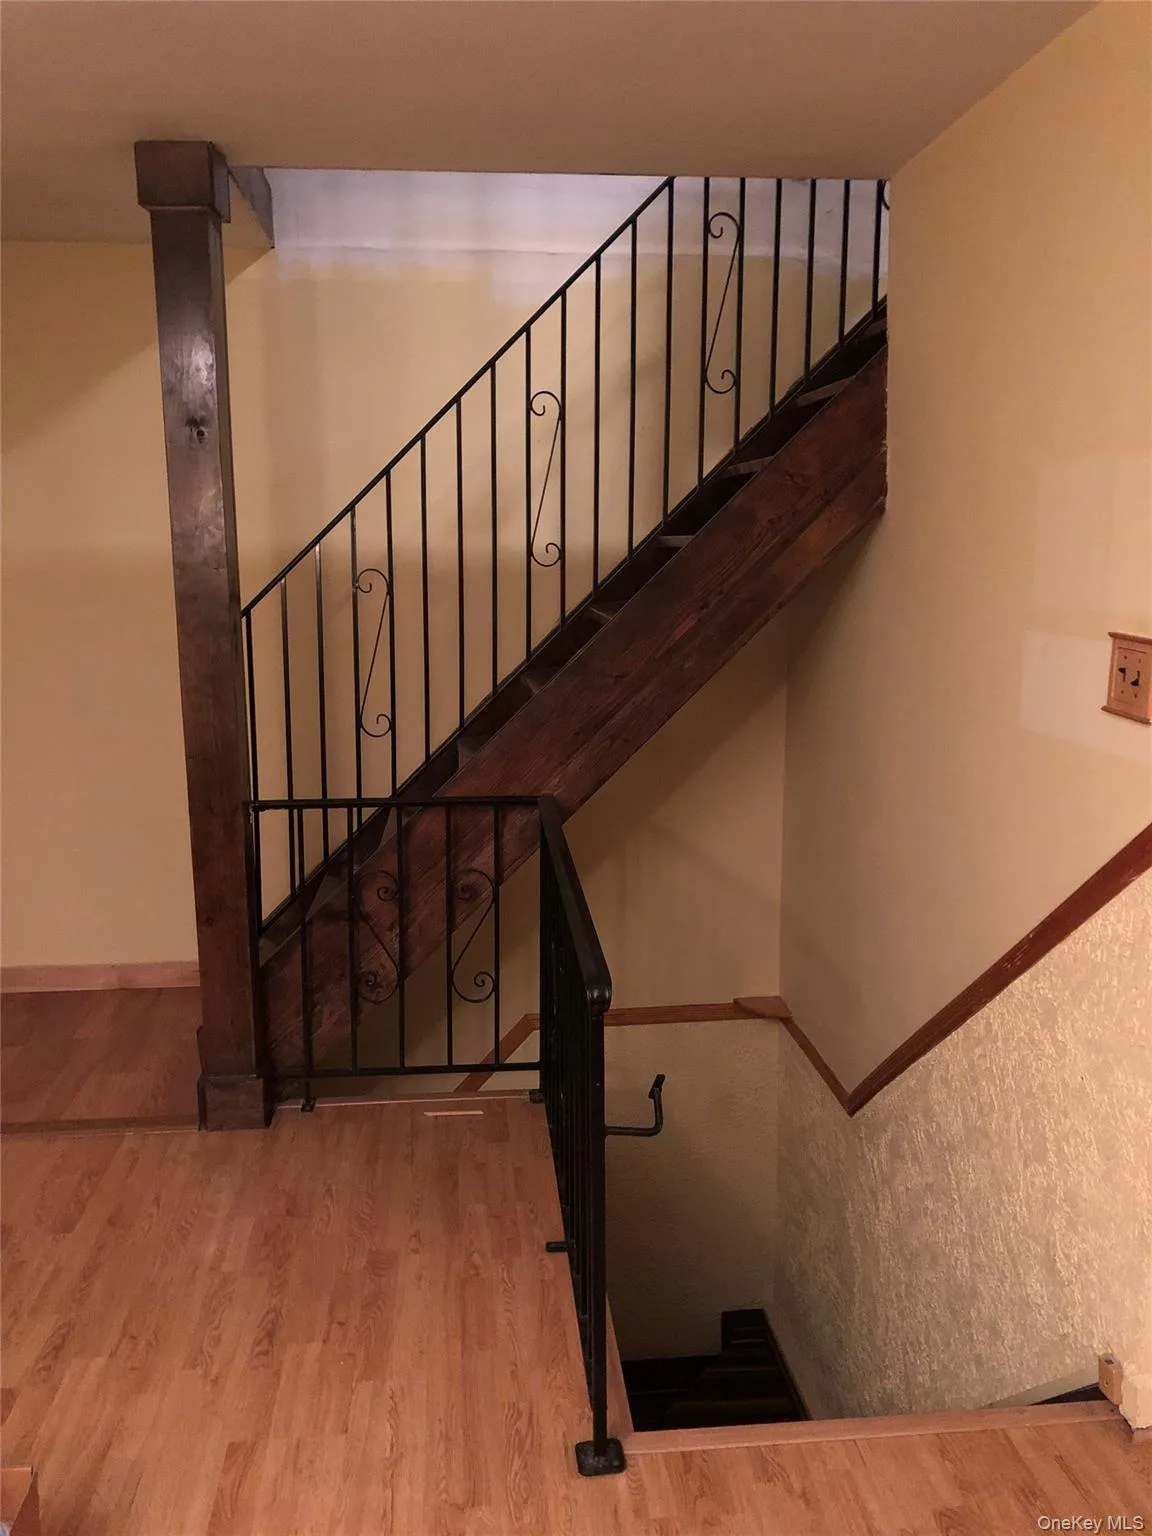 $279K
261-29 langston ave #b
Listing courtesy of Magic Of Great Neck Realty Inc
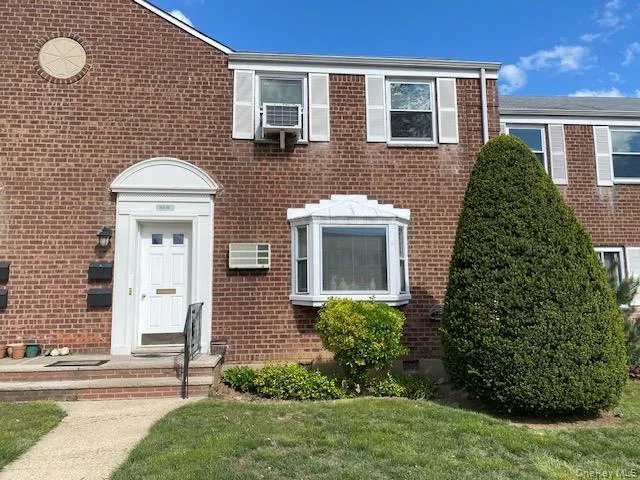 $260K
263-06 73rd Avenue #A-2
Listing courtesy of Miller & Miller Real Estate
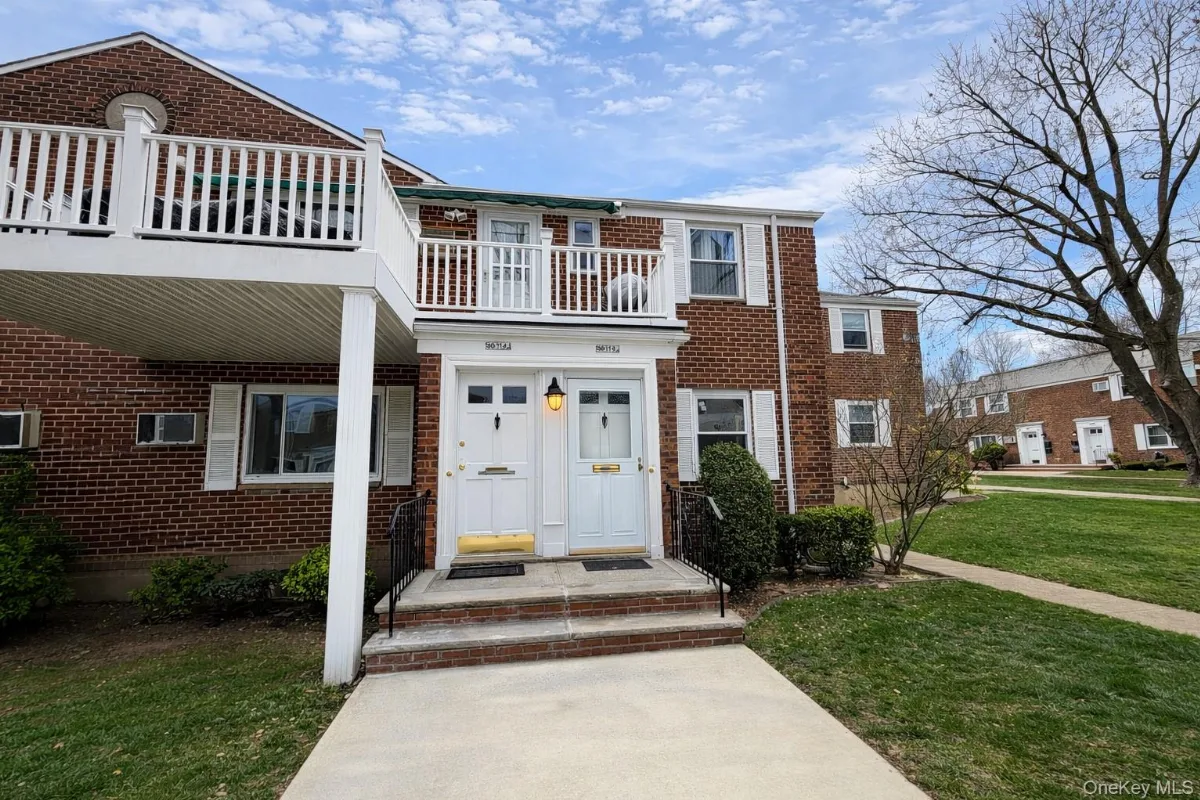 $395K
260-11 Langstone Avenue #GV118E5-1
Listing courtesy of Astoria Realty Brokerage Svcs
13 total on the market — showing the first 12.
What have Glen Oaks Village coops actually sold for?
57 units closed here over the past 24 months (38 in the last 12), with a 12-month median sale price around $380K and a typical 40 days to contract. We publish building-level aggregates here. The unit-by-unit sale history — which lines sold, at what price per room, and how each was marketed — we send on request.
The sale history covers the whole Glen Oaks development. A valuation prices one specific unit — use it if you own here.
What does it take to buy in Glen Oaks Village?
Managed by Self-managed (Glen Oaks Village Owners, Inc.; 9-member volunteer board).
Buying here runs through the building itself: a board package documenting your finances and references, then a board interview. What this board actually requires — minimum down payment, debt-to-income, reserves after closing, sublet and pet rules — is specific to Glen Oaks Village and can be stricter than your lender’s guidelines. We confirm the current requirements directly with the managing agent before you offer, so you never learn them from a rejection.
Requirements are set by the building and change over time — always confirm the current rules with the managing agent before you offer. General information, not legal advice.
Where is Glen Oaks Village — and what else is nearby?
The red marker is Glen Oaks Village; dark markers are the other coop and condo developments we track in Queens — click any of them to open that building’s market page.
Commuting from Glen Oaks Village
Train times are typical scheduled rides; check the MTA for current schedules.
Comparing Glen Oaks Village to nearby coop developments
Ordered by distance from Glen Oaks Village — same-town neighbours first, then nearest. The numbers are positions in that order, not a ranking, and each development’s own figures are shown so the comparison is like for like.
-
1
North Shore Towers Floral Park · 0.6 mi away106 sold / 12 mo 27 for sale now $349K median ask 69 median days
-
2
Deepdale Gardens Little Neck · 0.8 mi away136 sold / 12 mo 41 for sale now $349K median ask 57 median days
-
3
Bell Park Manor Terrace Queens Village · 1.9 mi away30 sold / 12 mo 33 for sale now $299K median ask 53 median days
-
4
Windsor Park Oakland Gardens · 2.5 mi away29 sold / 12 mo 16 for sale now $298K median ask 50 median days
Get a feel for the Glen Oaks area


Glen Oaks Coop Questions, Answered
What is the coop board approval process in Glen Oaks?
After a signed contract, the buyer submits a board package — typically a financial statement, tax returns, bank statements, reference letters, and the purchase application — followed by a board interview. Boards can decline without stating a reason (subject to fair-housing and other anti-discrimination laws). Timelines vary by building. A well-prepared package is the single biggest thing a buyer controls.
What happens at a coop board interview, and how should I prepare?
Most boards interview after reviewing your financial package — usually a short in-person or video meeting with a handful of board members. Expect questions about your finances, why you want to live in the building, and how you'll use the apartment; boards are gauging fit as much as qualification, and they cannot legally ask about protected categories like family status, religion, or national origin. The best preparation is a clean, complete board package beforehand — interviews go smoothly when there's nothing left for the board to ask about.
What does coop maintenance actually cover?
Maintenance is your monthly payment to the coop corporation, and it is one bill covering several things at once: the building's property taxes, your share of the underlying mortgage if the building carries one, staff and day-to-day operations, insurance, and contributions to reserves. Because the property taxes sit inside it, a portion of your maintenance is typically tax-deductible — your accountant can tell you which portion for a given building. The current maintenance figure appears on every coop listing we show. One note if you are comparing against condos: a condo's common charges exclude taxes and any underlying mortgage, so a coop maintenance figure will look higher for the same apartment without actually costing more.
How much do I need to put down on a coop?
Each coop building sets its own minimum, and it is a building rule rather than a lender rule — so it applies even to a buyer a bank would happily approve. Of the 997 co-op corporations whose minimum down payment we have confirmed from MLS listings, 75% require 20%, 16% allow 10%, and 8% require 25% or more. Some also require post-closing liquidity — months of mortgage and maintenance held in reserve after closing — on top of the down payment. We publish the confirmed minimum on the building pages where we can verify it, and confirm it listing by listing otherwise.
What debt-to-income ratio do coop boards look for?
Many boards set a maximum share of your gross income that your total housing costs and debt payments may take up. The threshold, and how strictly it's enforced, is set by each building. It's a board policy, not a lender requirement, and it's worth checking before you fall for a unit that a particular building's math won't support.
What is a post-closing liquidity requirement?
Some coop boards require you to keep a set amount of cash or liquid assets, measured in months of mortgage and maintenance payments, in reserve after your closing costs and down payment are paid, as proof you can weather a job loss or emergency without falling behind. It's on top of the down payment, not part of it, and requirements vary widely by building.
What is a sponsor unit, and can I buy a coop without board approval?
A sponsor unit is an apartment still owned by the entity that originally converted the building to a coop, rather than by an individual shareholder. Sponsor sales commonly skip the financial-package-and-interview process a resale requires, though the sponsor may still have its own approval or financing conditions, and house rules like sublet limits still apply once you own it. Sponsor units are worth asking about specifically if board approval is your biggest concern.
How can I check a coop building's finances before buying?
The board package process gives you access to the building's financial statements, board meeting minutes, reserve fund balance, and any pending assessments or litigation — an accountant or attorney can spot warning signs like thin reserves, rising underlying debt, or deferred maintenance that a listing description won't mention. This is exactly where having an attorney's eye on your deal from the start pays off, rather than discovering an issue after you're under contract.
What is a flip tax and who pays it?
A flip tax is a transfer fee charged by the coop corporation when a unit sells — commonly a percentage of the sale price or a per-share amount. Who pays it is set by the building's rules and the contract, and it varies by building. It belongs in any serious net-proceeds estimate, which is why our seller conversations start with the building's actual rules.
Can I sublet a coop apartment?
Only if the building allows it. Sublet policies range from prohibited, to allowed after a minimum period of owner occupancy, to allowed with board approval and fees. If rental flexibility matters to you, the proprietary lease and house rules need to be checked before you make an offer — not after.
Why are coop monthly charges higher than condo common charges?
Coop maintenance usually bundles the building's underlying mortgage and property taxes along with operations — condo owners pay property taxes separately. So a coop's higher monthly number is not automatically a worse deal; part of it may also be tax-deductible. Comparing a coop and condo fairly means comparing the all-in monthly cost, which we break down for every listing we work on.
Listings courtesy of OneKey® MLS as distributed by MLS GRID.
Based on information submitted to the MLS GRID as of October 10, 2026 8:45 pm. All data is obtained from various sources and may not have been verified by broker or MLS GRID. Supplied Open House Information is subject to change without notice. All information should be independently reviewed and verified for accuracy. Properties may or may not be listed by the office/agent presenting the information.
Personal-use terms and which listings this site shows: MLS & Data Disclosures
The DeVito Team of Keller Williams Realty Greater Nassau
Joseph DeVito, NY Licensed Associate Real Estate Broker
400 Garden City Plaza Ste 438, Garden City, NY 11530 · (516) 770-3782